
California Proposition 37: What Happens Next for Homebuyers?
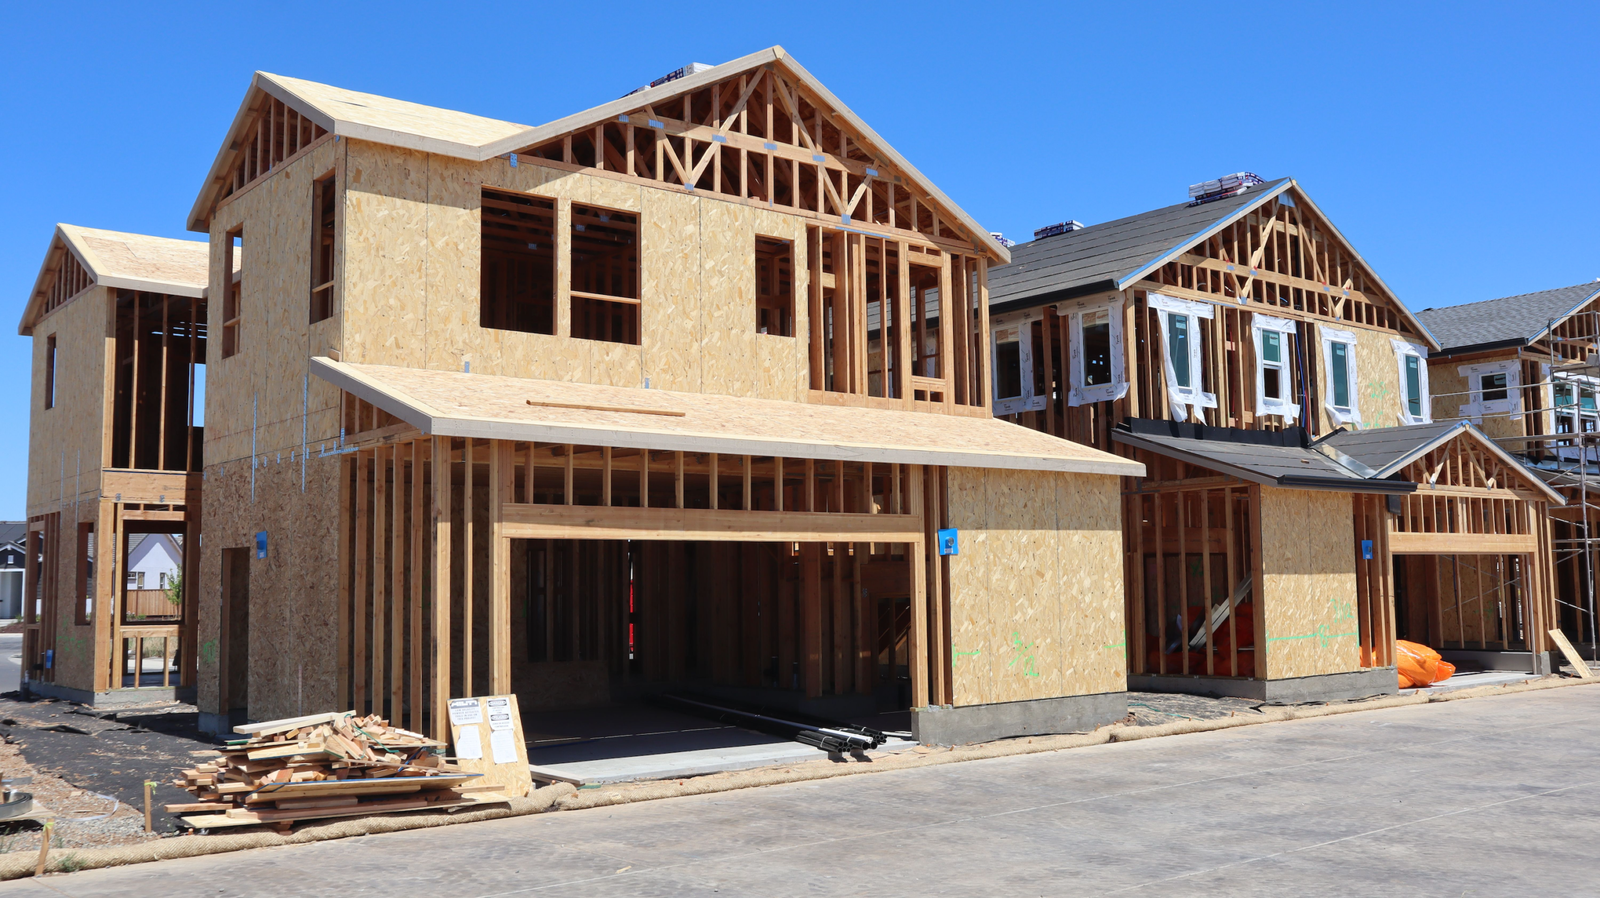
California voters approved Proposition 37 in the November 2026 general election, according to KCRA. The measure authorizes a homebuyer loan program intended to help eligible Californians purchase newly constructed homes. Approval is an important first step, but it does not mean buyers can apply immediately.
The program’s central feature is a second mortgage of up to 17% of an eligible home’s purchase price. Buyers would contribute at least 3% of the price and obtain a first mortgage for the remaining financing. The second mortgage is a loan, not a grant, and its payments and repayment terms will matter when evaluating affordability.
What needs to happen before the program opens?
The California Housing Finance Agency (CalHFA) must establish and administer the program. Buyers should watch for official guidance on underwriting, loan documentation, participating lenders, eligible properties, and application dates.
The rollout also requires a way to verify that newly constructed homes and participating builders meet program requirements. Although the initiative materials described a builder-certification process, buyers should rely on CalHFA’s published procedures before assuming a particular home qualifies.
How will the loans be funded?
Proposition 37 authorizes up to $25 billion in revenue bonds to finance the program. That is a funding ceiling—not a guarantee that all bonds will be issued at once or that assistance will be available to every eligible applicant.
Revenue bonds are intended to be repaid from program-related revenues rather than through a general-obligation pledge of state tax dollars. Buyers should still focus on their own obligation: a second mortgage must be repaid according to its loan terms.
What could financing look like?
For a hypothetical $700,000 eligible newly built home, a buyer receiving the maximum 17% second mortgage might assemble the purchase financing this way:
| Source of funds | Amount |
|---|---|
| Buyer contribution of 3% | $21,000 |
| Second mortgage of 17% | $119,000 |
| First mortgage for the remaining 80% | $560,000 |
This is an illustration, not a loan offer. Assistance could be less than the maximum, and closing costs, reserves, and other expenses may increase the cash needed. A smaller upfront contribution also does not necessarily mean a lower monthly payment.
Who may qualify?
The program is intended for buyers who meet California residency, household-income, occupancy, and financing requirements. The measure’s eligibility framework includes at least one year of California residency, a buyer contribution of at least 3%, and an income limit tied to 200% of the area median income. Because area median income varies by location and household circumstances, buyers should wait for CalHFA’s published eligibility guidance before deciding whether they qualify.
The home must also meet the program’s new-construction requirements; buyers should not assume an existing resale home is eligible. The program materials describe occupancy and loan protections, including fixed-rate financing and restrictions on prepayment penalties. CalHFA’s final guidance and the lender’s loan documents will be the sources to check for how those provisions apply.
What should buyers do next?
Before making an offer that depends on Proposition 37 assistance, confirm these five points with CalHFA and a participating lender:
- Program availability: Are applications open, and is funding available?
- Buyer eligibility: Do your income, residency, occupancy plans, and finances meet the rules?
- Home eligibility: Has the newly constructed property been verified for the program?
- Loan costs: What are the rates, payments, fees, and repayment terms of both mortgages?
- Cash to close: What will you need beyond the minimum 3% contribution?
Proposition 37 may create another path to homeownership for qualifying buyers. For now, the distinction is simple: voter approval authorizes the program; CalHFA’s rollout will determine when and how buyers can use it.
Thinking about selling in Ventura County? Contact me through monicagamble.realtor. We can identify which preparations deserve your attention before you commit to a renovation.